CAIA Charterholder · CFA Level III Candidate · MBA (UCLA Anderson) · B.Tech (Indian Institute of Technology) pramodty@gmail.com

Consulting · Products · Austin, TX · San Antonio, TX

Translating Complex Data into Robust, Uncertainty-Aware Financial Systems

From institutional multi-asset risk frameworks to automated CRE due diligence models.

I Consulting

Institutional Quantitative Risk & AI

For pensions, quant funds, risk teams, and LPs who evaluate mathematically rigorous, uncertainty-aware frameworks.

  • Probabilistic modeling & Bayesian risk frameworks
  • Hidden Markov models & regime-switching alpha
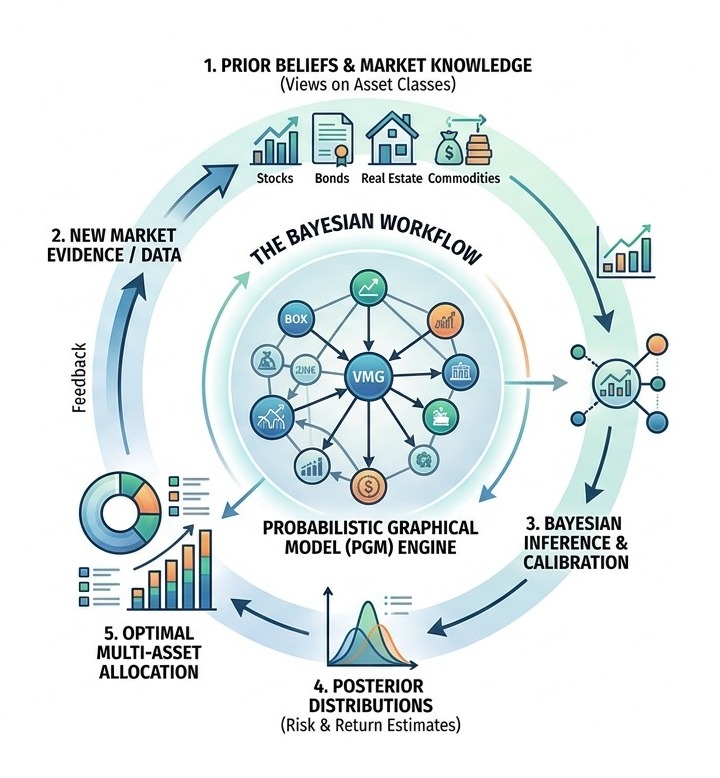
  • Black-Litterman Bayesian Networks / DAGs / DCGs & view-adjusted allocation
Explore institutional solutions →

II Consulting

CRE Engineering & Due Diligence Systems

For engineering firms, inspectors, and lenders who need operational friction removed from their report pipeline.

  • ASTM E2018-24 capital reserve modeling
  • PDF / field-note to Excel pro-forma automation
  • Lender-ready formatting & report backlog clearance
Explore CRE services →

III Product

Meridian — Unified Decision & Underwriting System

Institutional look-through and Bayesian analytics for mixed public/private portfolios — bridging sparse private-asset data with real-time public markets.

  • Unified look-through across REITs, CRE, private debt
  • Bayesian un-smoothing with full audit lineage
  • In-memory DuckDB + FastAPI engine, no durable plaintext
Full deck ↗
I

Institutional Probabilistic Analytics & Risk Consulting

Rigorous, uncertainty-aware frameworks for institutions that need decisions to survive a risk committee. Three solution modules, one for each sub-audience.

Allocators & pension funds

Multi-asset risk-budgeting & structural allocation under uncertainty

Problem
Traditional mean-variance optimization breaks out-of-sample due to extreme sensitivity to expected-return inputs.
Deliverable
Custom hierarchical Bayesian shrinkage & Black-Litterman Directed Acyclic Graph (DAG) models.
Value
Absorbs subjective market views, buffers against tail risk, and stabilizes asset weights across changing macro regimes without over-concentrating positions.

Quant funds & systematic alpha

Causal discovery & regime-switching market mechanics

Problem
Linear backtests overfit static historical distributions and break down during structural regime shifts.
Deliverable
PyMC/JAX-driven Hidden Markov Models (HMMs) with Student-t emission distributions and causal d-separation frameworks.
Value
Isolates true causal alpha drivers from latent market noise and enables dynamic real-time risk / volatility targeting.

Risk teams & LPs / GPs

Probabilistic performance attribution & style-drift identification

Problem
Retrospective Brinson-Fachler models fail to separate true manager selection skill from accidental factor / sector tilts.
Deliverable
Latent-variable hierarchical attribution frameworks.
Value
Decouples alpha, selection skill, and market friction into dynamic latent states — flagging hidden style drift before it compromises fund performance.

Meridian began as this practice's proof-of-concept for Bayesian un-smoothing: P(Vreal | Mpublic) ∝ P(Mpublic | Vreal) · P(Vappraisal), reconciling real-time public-market signals with smoothed private appraisals across mixed public/private portfolios.

II

Fractional Due Diligence & Engineering Workflow Analytics

Clear your report backlog. Scale inspection volume without adding fixed overhead.

Field engineers excel at physical site walks and structural assessments — not spending hours wrestling with ASTM spreadsheets and formatting 12-year Capital Reserves tables. I serve as a backend financial analytics desk for engineering firms, translating raw field notes and draft PDFs into institutional-grade, lender-ready Excel pro-formas.

ASTM E2018-24 Capital Reserve Automation

Convert raw field observations into formula-linked, multi-scenario 12-year reserve tables.

Lender & Private Equity Formatting

Standardize technical engineering findings directly into institutional CRE underwriting templates.

Report Backlog Clearance

Zero field liability — a fractional analytics and production desk that helps senior engineers double weekly inspection capacity.

Zero field liability: physical observations, EULs, ERULs, and unit costs stay with your field observer. Under the hood, this pipeline is Meridian's Document-to-Model Engine (FastAPI + DuckDB + PDF transclusion) — the technology that parses engineering reports and Excel DCFs into the pro-forma. Sample deliverable: a two-asset data-center + industrial-warehouse dashboard — preview the workbook →. To review the live Excel file, request access via pramodty@gmail.com.

Career Path

Teachers Retirement System of Texas

Performance measurement · ~$200B multi-asset trust

Production performance infrastructure across funds, aggregates, and composites. Multi-decade validated history used for research and governance.

USAA Real Estate

Enterprise performance & attribution

Institutionalized traceability standards that corrected reported performance by ≥450 bp in key asset classes. NCREIF / MSCI methodology work.

GE Capital Real Estate

Risk & analytics · ~$80B CRE book

Stress framework presented to Federal Reserve oversight. Underwriting and syndication systems on ~$3B of complex transactions.

Independent CRE practice

Underwriting · asset management

Acquisition support on ~$100–300M multifamily and creative office. First comprehensive budgeting framework for a large SFR platform (~30,000 units).

~$200BPerformance monitoring & attribution of the trust platform at a pension fund
≥450 bpReporting correction at USAA RE
~$80BCRE book stress-tested at GE
25+ yrsPublic markets + private CRE

Full career history, credentials, and technical appendix on the résumé page →.

How to start

Engineering firms: send a redacted field-note pack or a draft PCR. I return a scoped workbook and a turnaround time. Allocators and risk teams: a 30-minute call on the decision that is currently made with a point estimate.

Austin, Texas · Independent consultant · Field inspections stay with your team · Not investment advice